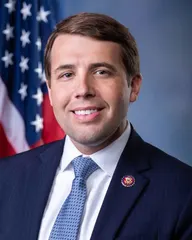
Chris Pappas
U.S. Representative for New Hampshire's 1st District (Democrat). In the House since 2019.
What they work on
- Armed Forces and National Security10 bills
- Crime and Law Enforcement8 bills
- Energy6 bills
What Chris Pappas did
The biggest votes
One Big Beautiful Bill Act
This bill reduces taxes, reduces or increases spending for various federal programs, increases the statutory debt limit, and otherwise addresses agencies and programs throughout the federal government.
What this bill does
Every Democrat voted no; nearly every Republican voted yes.
Rescissions Act of 2025
This bill rescinds $9.4 billion in unobligated funds that were provided to the Department of State, the U.S. Agency for International Development (USAID), various independent and related agencies, and the Corporation for Public Broadcasting.
What this bill does
Nearly every Democrat voted no; nearly every Republican voted yes.
Continuing Appropriations, Agriculture, Legislative Branch, Military Construction and Veterans Affairs, and Extensions Act, 2026
This act ends the government shutdown that began on October 1, 2025, by providing FY2026 continuing appropriations for most federal agencies through January 30, 2026, and providing appropriations through the end of FY2026 for agriculture, military construction and veterans affairs, and legislative branch programs.
What this bill does
Nearly every Democrat voted no; nearly every Republican voted yes.
What else they did
Northeast Lobsterman Protection Act of 2026
This bill extends the deadline from 2028 to 2035 for the National Marine Fisheries Service to issue new regulations that protect the endangered Atlantic large whale from certain lobster and crab fishing gear.
What this bill does
Veterans’ Transition to Trucking Act of 2025
This bill authorizes the Department of Veterans Affairs (VA) to act as a state approving agency to approve multi-state apprenticeship programs (i.e., non-federal apprenticeship programs operating in more than one state) for purposes of VA educational assistance benefits.
6 cosponsors, all from the other party.
End the Cyprus Embargo Act
To provide for nonapplicability of a policy of denial for exports, re-exports, or transfers of defense articles and defense services destined for or originating in the Republic of Cyprus.
12 cosponsors, 5 of them from the other party.
Protect America's Workforce Act
This bill nullifies the Executive Order titled Exclusions from Federal Labor-Management Relations Programs (issued on March 27, 2025), which excludes specified executive agencies and subdivisions from the Federal Service Labor-Management Relations Statute.
What this bill does
The 3rd member to sign.
One Big Beautiful Bill Act
Stop Insider Trading Act
This bill generally prohibits Members of Congress and their spouses and dependent children from purchasing stocks and requires public notice before these individuals may sell stocks.
What this bill does
Money
Biggest PAC givers: Norpac and Professional Aviation Safety Specialists PAC
Raised $15.4 million for the 2026 election, through August 19, 2026; 7% came from PACs and other political committees.
Votes through September 16, 2026. Campaign money through August 19, 2026.
In numbers
669 of 676 recorded votes99.0%
419 of 467 votes where the two parties disagreed89.7%
Bills since January 2025
- Sponsored
- 59
- Cosponsored
- 376
Stock trades
No stock trade reports were filed from 2019 to 2026.
- Individuals$13,527,025.65 (87.9%)
- PACs and other committees$1,104,872.76 (7.2%)
- Party committees$1,500 (<0.1%)
- Other receipts$751,258.42 (4.9%)
Cash on hand on August 19, 2026: $4.25 million
Other committees also gave $10,000.
Sources: House Clerk, U.S. Government Publishing Office, Bill status bulk data: Senate bills, 119th Congress, Bill status bulk data: House joint resolutions, 119th Congress, Bill status bulk data: Senate joint resolutions, 119th Congress, Bill status bulk data: House concurrent resolutions, 119th Congress, Bill status bulk data: Senate concurrent resolutions, 119th Congress, Bill status bulk data: House simple resolutions, 119th Congress, Bill status bulk data: Senate simple resolutions, 119th Congress, House financial disclosure, House financial disclosure index, reporting year 2025 (2025FD.zip), House financial disclosure index, reporting year 2024 (2024FD.zip), House financial disclosure index, reporting year 2023 (2023FD.zip), House financial disclosure index, reporting year 2022 (2022FD.zip), House financial disclosure index, reporting year 2021 (2021FD.zip), House financial disclosure index, reporting year 2020 (2020FD.zip), House financial disclosure index, reporting year 2019 (2019FD.zip), Federal Election Commission, Contributions and independent expenditures from committees to candidates, 2025–2026 (pas226.zip), Committee master, 2025–2026 (cm26.zip)
All votes since January 2025Voted yes or no on 669 of 676 recorded votesShow details
Votes since January 2025
House votes from January 3, 2025, to September 16, 2026
- Attendance
- Voted yes or no on 669 of 676 (99.0%) recorded votes.Voted “present” 6 times.
- With their party
- Voted with most of their party on 419 of 467 (89.7%) votes where the two parties disagreed.
Source: House Clerk
Most recent votes
| Date | Question | Bill | Their vote | Result |
|---|---|---|---|---|
| Sep 16, 2026 | Passage under fast-track rules (two-thirds needed) Retire through Ownership Act What the bill doesRetire through Ownership Act
This bill allows the fiduciary of an Employee Stock Ownership Plan (ESOP) to rely on a valuation provided by an independent valuation expert or business appraiser in determining the fair market value of the plan's securities if the securities are not traded on a national securities exchange (i.e., not publicly traded) and the expert or appraiser follows specified methodologies.
In general, ESOPs are defined contribution pension plans where employees accrue shares of their employers' stock in individual accounts as part of their compensation. After separating from employment or retiring, employees receive the cash value of their shares.
Under the bill, an independent expert or appraiser must adhere to the methodology established under the Internal Revenue Service Ruling 59-60, which prescribes the factors a professional business appraiser should consider in forming a valuation of the stock for a closely held business. | S. 2403 | Yes | Passed 401 to 14[source] |
| Sep 16, 2026 | Passage under fast-track rules (two-thirds needed) Water Resources Development Act What the bill doesWater Resources Development Act of 2026
This bill authorizes and modifies certain water resource infrastructure projects and programs of the U.S. Army Corps of Engineers and makes related requirements. For example, the bill authorizes and modifies various water resources feasibility studies and projects of the Corps of Engineers, such as studies or projects to
- maintain ports and harbors,
- make certain waterways more navigable,
- reduce flood and storm damage,
- restore aquatic ecosystems and protect fish and wildlife,
- protect shorelines,
- address harmful algal blooms,
- rehabilitate dams,
- manage recreational sites and facilities,
- support water supply and storage projects, and
- support other water resources infrastructure.
The bill also directs the Corps of Engineers to establish an Office on Alternative Delivery Methods in order to accelerate project delivery of infrastructure.
In addition, the bill directs the Corps of Engineers to issue a rule that establishes categorical permissions for certain harbor or river improvements that will cause only minimal adverse environmental effects. | H.R. 9497 | Yes | Passed 415 to 9[source] |
| Sep 16, 2026 | Passage under fast-track rules (two-thirds needed) Ratepayer Protection Act What the bill doesRatepayer Protection Act
The bill requires state utility regulators and nonregulated utilities to consider implementing a standard to hold certain large-load customers responsible for the costs associated with any generation, transmission, or distribution upgrade of electric service necessary to serve such customers. A large-load customer means a non-residential electric consumer that enters, or requests to enter, an agreement concerning the sale of electric energy primarily to operate information technology infrastructure and related systems pertaining to data storage and computational applications and services (e.g., data centers) that have a peak electric demand of 100 megawatts or more at a single site or campus.
Specifically, the bill requires states to consider implementing a federal standard for large-load customers. The standard must require rates charged by electric utilities for providing electric service to a large-load customer to be designed to recover from the large-load customer the full, incremental cost of any generation, transmission, or distribution upgrade necessary to serve such customer. This rate must include the costs that would be incurred if the large-load customer terminates an agreement with the electric utility pertaining to the sale of electric energy or otherwise ceases the purchase of energy from the electric utility.
Under the standard, an electric utility must require the large-load customer to provide to the utility financial assurances or contributions to cover the cost of any generation, transmission, or distribution upgrade that is necessary to serve the load of a large-load customer before the utility makes any generation, transmission, or distribution upgrade. | H.R. 9340 | Yes | Passed 417 to 3[source] |
| Sep 16, 2026 | Final passageProviding for congressional disapproval under chapter 8 of title 5, United States Code, of the rule issued by the Environmental Protection… moreAgency relating to the “California State Nonroad Engine Pollution Control Standards; Commercial Harbor Craft Regulations; Notice of Decision”What the bill doesThis joint resolution revokes the partial authorization granted to the California Air Resources Board (CARB) to amend its Commercial Harbor Craft regulation. Among other elements, the amendments proposed by CARB and partially authorized by the Environmental Protection Agency (EPA) create new emission standards and compliance dates depending on vessel category and engine model year and expand the types of vessels covered by the regulation (e.g. commercial fishing boats). (Under the Clean Air Act, the EPA may authorize California to adopt and enforce standards relating to the control of emissions from nonroad vehicles or engines if those standards meet certain requirements.)
Specifically, the joint resolution nullifies the EPA authorization decision titled California State Nonroad Engine Pollution Control Standards; Commercial Harbor Craft Regulations; Notice of Decision. | H.J.Res. 213 | No | Passed 214 to 208[source] |
| Sep 16, 2026 | Final passage PROOF Act What the bill doesPreventing Rip-offs and Obtaining Oversight of Funds Act or the PROOF Act
This bill requires states to provide such information as the Department of Justice (DOJ) may require for the purpose of investigating or prosecuting alleged fraud committed with regard to certain federally funded programs.
Programs covered by this requirement include:
- Medicaid,
- Supplemental Nutrition Assistance Program (SNAP),
- Temporary Assistance for Needy Families (TANF),
- certain federal payments and grants to state governments related to the coronavirus response, and
- any other program to which funds are made available to states and identified by DOJ as vulnerable to fraud.
A federal agency may only use such information for law enforcement purposes related to fraud and may not disclose it for any unrelated administrative or commercial purpose.
DOJ must annually report to Congress on the number of requests for information issued to state agencies under this bill, the programs with respect to which such requests were made, and the number of fraud investigations initiated and convictions secured using the information obtained. | H.R. 10326 | No | Passed 217 to 207[source] |
| Sep 16, 2026 | Final passage National Fraud Enforcement Division Act What the bill doesNational Fraud Enforcement Division Act of 2026
This bill provides statutory authority for the National Fraud Enforcement Division within the Department of Justice (DOJ). The division investigates and prosecutes fraud against taxpayer dollars and taxpayer-funded programs.
The National Fraud Enforcement Division was established by DOJ in April 2026. | H.R. 9576 | Yes | Passed 352 to 72[source] |
| Sep 16, 2026 | Motion to Concur in the Senate Amendments An Act to amend the Internal Revenue Code of 1986 to allow early childhood educators to take the educator expense deduction, and for other purposes What the bill doesLindsey O. Graham Sanctioning Russia and Iran Act of 2026
This bill imposes a variety of sanctions, tariffs, and prohibitions related to Russia, extends an Iran-related sanctions law, and expands a tax deduction for teacher expenses to include early childhood educators.
For example, under the bill, the President must impose visa- and property-blocking sanctions on specified persons (individuals and entities) such as the Russian president and certain Russian military commanders. The President must also increase the rate of duty up to 100% ad valorem (i.e., relative to the value) on all goods imported into the United States from a country that was among the five largest importers of Russian-origin crude oil or natural gas if such country knowingly makes new purchases of such products after enactment of the bill.
The bill prohibits (1) the export, reexport, or in-country transfer to or in Russia of any U.S.-produced energy or energy product; (2) U.S. persons from making new investments in Russia or purchasing Russian sovereign debt; and (3) trading the securities of Russian government-owned, -controlled, or -affiliated entities on U.S. national securities exchanges.
The bill extends through 2031 the Iran Sanctions Act of 1996, which requires the President, with some exceptions, to impose sanctions on certain persons engaged in specified transactions related to Iran's energy sector or Iran's efforts to acquire or develop certain weapons.
The bill expands eligibility for federal tax deductions of certain educator expenses to early childhood educators providing educational or childcare services to those under age 6. | H.R. 5334 | No | Passed 262 to 159[source] |
| Sep 15, 2026 | Agreeing to the Resolution Directing the President, pursuant to section 5(c) of the War Powers Resolution, to remove United States Armed Forces from hostilities with Iran What the bill doesThis concurrent resolution directs the President to remove U.S. Armed Forces from hostilities against Iran unless explicitly authorized by a declaration of war or a congressional authorization for use of military force against Iran.
Elements of the U.S. Armed Forces needed to defend the United States, an ally, or a partner from imminent attack are not covered by this requirement provided the President complies with a specified provision of the War Powers Resolution. (The provision generally requires the President to remove U.S. Armed Forces from hostilities no more than 60 days after the President notifies or is required to notify Congress of such involvement, unless Congress authorizes such use. For more information on the War Powers Resolution, see CRS In Focus 13134.) | H.Con.Res. 93 | Yes | Passed 220 to 204[source] |
| Sep 15, 2026 | Final passageProviding for congressional disapproval under chapter 8 of title 5, United States Code, of the rule submitted by the Environmental… moreProtection Agency relating to “California State Nonroad Engine Pollution Control Standards; Ocean-Going Vessels At-Berth; Notice of Decision”What the bill doesThis joint resolution revokes the authorization granted to the California Air Resources Board (CARB) to amend its Ocean-Going Vessels At-Berth Regulation. Among other elements, the amendment proposed by CARB and authorized by the Environmental Protection Agency (EPA) expanded auxiliary engine emissions reductions requirements to include additional categories of ocean-going vessels. (Under the Clean Air Act, the EPA may authorize California to adopt and enforce standards relating to the control of emissions from nonroad vehicles or engines if those standards meet certain requirements.)
Specifically, the joint resolution nullifies the EPA authorization decision titled California State Nonroad Engine Pollution Control Standards; Ocean-Going Vessels At-Berth; Notice of Decision. | H.J.Res. 210 | No | Passed 216 to 211[source] |
| Sep 15, 2026 | Passage under fast-track rules (two-thirds needed) Tax Relief for Fraud Victims Act What the bill doesTax Relief for Fraud Victims Act
This bill expands the federal tax deduction for personal casualty and theft losses by eliminating certain limits, including the requirement that such losses arise from certain disasters. The bill also extends the tax refund deadline and modifies certain retirement plan rules related to certain fraud losses.
The bill repeals the limit on the federal tax deduction for personal casualty losses (not attributable to a trade, business, or transaction entered into for profit) that allows such losses only if arising from a federal or state declared disaster or to the extent that such losses offset personal casualty gains.
The bill allows taxpayers to elect to claim a tax deduction for losses arising from a theft involving fraud, deceit, or misrepresentation in the tax year such losses occur (rather than in the tax year discovered). Further, the bill extends the deadline for a refund claim related to a tax deduction for such losses to no less than one year after the date on which the losses are discovered and eliminates certain restrictions on the amount of such refund.
For early distributions from a qualified retirement plan arising from a theft loss involving fraud, deceit, or misrepresentation for which a tax deduction is allowed, the bill
- waives the 10% penalty,
- extends the deadline for filing a refund claim and eliminates certain restrictions on the amount of such refund, and
- allows one year (beginning on the day after the theft loss is discovered) to repay such early distributions. | H.R. 9500 | Yes | Passed 408 to 17[source] |
All billsSponsored 59Show details
Bills since January 2025
- Sponsored
- 59 bills and resolutions
- Cosponsored
- 376 bills and resolutions
Sources: U.S. Government Publishing Office, Bill status bulk data: Senate bills, 119th Congress, Bill status bulk data: House joint resolutions, 119th Congress, Bill status bulk data: Senate joint resolutions, 119th Congress, Bill status bulk data: House concurrent resolutions, 119th Congress, Bill status bulk data: Senate concurrent resolutions, 119th Congress, Bill status bulk data: House simple resolutions, 119th Congress, Bill status bulk data: Senate simple resolutions, 119th Congress
Sponsored, most recently introduced first
Consumer Fuel Costs Relief Act
Introduced September 24, 2026. In committee; no vote yet. Last action on September 24, 2026.[source]
Introduced September 24, 2026. In committee; no vote yet. Last action on September 24, 2026.[source]
Introduced September 24, 2026. In committee; no vote yet. Last action on September 24, 2026.[source]
Introduced July 27, 2026. In committee; no vote yet. Last action on July 27, 2026.[source]
Investing in State Energy Act of 2026
Introduced July 23, 2026. In committee; no vote yet. Last action on July 23, 2026.[source]
Introduced July 16, 2026. In committee; no vote yet. Last action on July 16, 2026.[source]
Introduced June 30, 2026. In committee; no vote yet. Last action on June 30, 2026.[source]
SAFEGUARD Veterans Act of 2026
Introduced June 2, 2026. In committee; no vote yet. Last action on June 23, 2026.[source]
ATIIP Reauthorization and Improvement Act
Introduced April 29, 2026. In committee; no vote yet. Last action on April 29, 2026.[source]
Protecting American Railroad Workers’ Jobs Act of 2026
Introduced April 23, 2026. In committee; no vote yet. Last action on April 23, 2026.[source]
Introduced April 22, 2026. In committee; no vote yet. Last action on April 22, 2026.[source]
Introduced April 21, 2026. In committee; no vote yet. Last action on April 21, 2026.[source]
Introduced April 21, 2026. In committee; no vote yet. Last action on April 21, 2026.[source]
Introduced April 16, 2026. In committee; no vote yet. Last action on April 16, 2026.[source]
Introduced April 9, 2026. In committee; no vote yet. Last action on April 9, 2026.[source]
…and 44 more sponsored items.
Most recent cosponsorships
Motorsports Fairness and Permanency Act of 2025
Cosponsored September 28, 2026. In committee; no vote yet. Last action on March 18, 2025.[source]
Title VIII Nursing Workforce Reauthorization Act of 2025
Cosponsored September 24, 2026. Forwarded by Subcommittee to Full Committee by Voice Vote. Last action on September 10, 2025.[source]
North Platte Canteen Congressional Gold Medal Act
Cosponsored September 24, 2026. In committee; no vote yet. Last action on February 21, 2025.[source]
Cosponsored September 24, 2026. In committee; no vote yet. Last action on September 2, 2026.[source]
Connected Vehicle Security Act of 2026
Cosponsored September 16, 2026. In committee; no vote yet. Last action on May 11, 2026.[source]
Reverse Big Ugly Tax Breaks for Data Centers Act
Cosponsored September 16, 2026 (original cosponsor). In committee; no vote yet. Last action on September 16, 2026.[source]
Cosponsored September 10, 2026 (original cosponsor). In committee; no vote yet. Last action on September 10, 2026.[source]
Cosponsored September 3, 2026 (original cosponsor). In committee; no vote yet. Last action on September 3, 2026.[source]
Congressional Pension Accountability Act
Cosponsored September 3, 2026 (original cosponsor). In committee; no vote yet. Last action on September 3, 2026.[source]
Stronger Start for Working Families Act
Cosponsored September 3, 2026 (original cosponsor). In committee; no vote yet. Last action on September 3, 2026.[source]
…and 366 more cosponsorships.
Campaign money$15.4 million raisedShow details
Campaign money, 2025 and 2026
House campaign, with activity through August 19, 2026. See it on FEC.gov ↗
The campaign's totals
- Raised
- $15,384,656.83
- Spent
- $11,540,323.25
- Cash on hand on August 19, 2026
- $4,251,917.81
Where the money came from
- Individuals
- $13,527,025.65
- PACs and other committees
- $1,104,872.76
- Party committees
- $1,500
Top contributing committees
The FEC reports $1.1 million from PACs and other committees. The largest givers:
| Committee | Amount |
|---|---|
| NorpacPAC, 1 contribution | $19,500 |
| Professional Aviation Safety Specialists PACPAC, 4 contributions | $10,000 |
| American Association for Justice Political Action Committee (AAJ PAC)PAC, 3 contributions | $10,000 |
| Air Line Pilots Association PACPAC, 2 contributions | $10,000 |
| America's Credit Unions PACPAC, 2 contributions | $10,000 |
| Progressive Turnout ProjectHybrid PAC (with Non-Contribution Account), 2 contributions | $10,000 |
| National Elevator Constructors Pac/ Intn'l Union of Elevator Constructors (NEC PAC)PAC, 3 contributions | $7,500 |
| International Association of Sheet Metal, Air, Rail and Transportation Workers Political Action LeaguePAC, 2 contributions | $7,500 |
| National Stone, Sand & Gravel Association RockpacPAC, 2 contributions | $7,500 |
| The Surety & Fidelity Association of America Political Action CommitteePAC, 2 contributions | $7,500 |
Outside spending
Outside groups spent $2,458 supporting them (2 groups).
| Committee | Amount |
|---|---|
| Dmfi PAC2 expenditures | $1,973 |
| Givegreen United Action7 expenditures | $485 |
Sources: Federal Election Commission, Contributions and independent expenditures from committees to candidates, 2025–2026 (pas226.zip), Committee master, 2025–2026 (cm26.zip)
Stock trades and holdingsNo stock trade reports foundShow details
Stock trades and holdings
No stock trade reports filed from 2019 to 2026.
Holdings in their 2025 annual report, filed August 13, 2026[PDF]
| Asset | Owner | Value (range) | Income type |
|---|---|---|---|
| Bank of America Checking xx23 | Self | $15,001 – $50,000 | Interest |
| Bank of America Savings xx25 | Self | $15,001 – $50,000 | Interest |
| PNC Bank Checking xx22 | Spouse | $1,001 – $15,000 | None |
| Puritan Confectionery Co. | Self | $1,000,001 – $5,000,000 | LLC Income |
| Uber Technologies | Spouse | $100,001 – $250,000 | None |
| Uber Technologies, Inc. Common Stock (UBER) | Spouse | $100,001 – $250,000 | None |
| Amazon.com, Inc. - Common Stock (AMZN)in Fidelity 401K | Spouse | $15,001 – $50,000 | None |
| Vanguard Target Retirement 2055 Fund (VFFVX)in Fidelity 401K | Spouse | $100,001 – $250,000 | Tax-Deferred |
| 207 Hooksett Roadin Pilgrim Realty | Self | $250,001 – $500,000 | LLC Income |
| 865 Maple Streetin Pilgrim Realty | Self | $15,001 – $50,000 | None |
| Alger Focus Equity Fund Class Z (ALZFX)in Wells Fargo IRA | Self | $15,001 – $50,000 | Tax-Deferred |
| American Funds New World Fund A (NEWFX)in Wells Fargo IRA | Self | $1,001 – $15,000 | Tax-Deferred |
| American Funds SMALLCAP World A (SMCWX)in Wells Fargo IRA | Self | $15,001 – $50,000 | Tax-Deferred |
| AQR Managed Futures Strategy Fund Class I (AQMIX)in Wells Fargo IRA | Self | $1,001 – $15,000 | Tax-Deferred |
| Artisan Developing World Fund - Advisor Shares (APDYX)in Wells Fargo IRA | Self | $1,001 – $15,000 | Tax-Deferred |
| Artisan International Value Fund Advisor Shares (APDKX)in Wells Fargo IRA | Self | $15,001 – $50,000 | Tax-Deferred |
| BNY Mellon Dynamic Value Fund Class I (DRGVX)in Wells Fargo IRA | Self | $15,001 – $50,000 | Tax-Deferred |
| BNY Mellon Natural Resources Fund Class I (DLDRX)in Wells Fargo IRA | Self | $1,001 – $15,000 | Tax-Deferred |
| BrandywineGLOBAL Corporate Credit Fund Class I (BCGIX)in Wells Fargo IRA | Self | $15,001 – $50,000 | Tax-Deferred |
| Fidelity Advisor Growth Opportunities Fund: Class I (FAGCX)in Wells Fargo IRA | Self | None | Tax-Deferred |
| Fidelity New Markets Income Fund Class I (FGZMX)in Wells Fargo IRA | Self | $1,001 – $15,000 | Tax-Deferred |
| Hennessy Cornerstone Growth Fund Institutional Class (HICGX)in Wells Fargo IRA | Self | $1,001 – $15,000 | Tax-Deferred |
| Invesco Developing Markets Fund Class Y (ODVYX)in Wells Fargo IRA | Self | None | Tax-Deferred |
| Invesco Small Cap Value Class Y (VSMIX)in Wells Fargo IRA | Self | None | Tax-Deferred |
| Invesco Value Opportunities Fund Class Y (VVOIX)in Wells Fargo IRA | Self | $1,001 – $15,000 | Tax-Deferred |
| LoCorr Macro Strategies Fund - Class I (LFMIX)in Wells Fargo IRA | Self | $1,001 – $15,000 | Tax-Deferred |
| Loomis Sayles Global Allocation Fund Class Y (LSWWX)in Wells Fargo IRA | Self | $1,001 – $15,000 | Tax-Deferred |
| MFS International Value Fund Class I (MINIX)in Wells Fargo IRA | Self | $15,001 – $50,000 | Tax-Deferred |
| Nuveen Preferred Securities Fund - Cl R (NPSRX)in Wells Fargo IRA | Self | $1,001 – $15,000 | Tax-Deferred |
| Parnassus Value Equity Fund Institutional Shares (PFPWX)in Wells Fargo IRA | Self | None | Tax-Deferred |
Showing 30 of 39 assets; the rest are in the linked filing.
Sources: House financial disclosure, House financial disclosure index, reporting year 2025 (2025FD.zip), House financial disclosure index, reporting year 2024 (2024FD.zip), House financial disclosure index, reporting year 2023 (2023FD.zip), House financial disclosure index, reporting year 2022 (2022FD.zip), House financial disclosure index, reporting year 2021 (2021FD.zip), House financial disclosure index, reporting year 2020 (2020FD.zip), House financial disclosure index, reporting year 2019 (2019FD.zip)
Their work since January 2025Show details
Their work since January 2025
Spoke on the floor 12 times on 12 days.[source] Topics included “Providing for Consideration of H.R. 1, One Big Beautiful Bill Act,” “Contitutional Authority Statement,” and the Medal of Honor Act.[source] Filed 32 written statements for the Record.[source]
Offered no amendments.[source]
Sits on the Veterans' Affairs Committee (70 hearings and 12 bill-drafting sessions, counting subcommittees) and the Transportation and Infrastructure Committee (45 hearings, 21 bill-drafting sessions).[Veterans' Affairs][Transportation and Infrastructure]
Signed 22 of the 27 discharge petitions filed since January 2025.[source] 5 of the 22 they signed forced a vote.
Their office spent $1.94 million of its $2.01 million budget for 2025, or 96% (the typical House office spent 97%), as reported through June 30, 2026.[spending][budget] Staff pay took $83 of every $100 (typical: $75).[spending] Official mail cost $3,767 (typical: $18,550).[spending]
Lobbyists reported $450,855 in 288 contributions in 2025 to their campaign or their leadership PAC.[source]
Floor speeches through October 5, 2026.
Senate Office of Public Records cannot vouch for the data or analyses derived from these data after the data have been retrieved from LDA.gov. Retrieved from LDA.gov on October 6, 2026.
Committees2 committeesShow details
Committees
- Committee on Transportation and InfrastructureMinority member
- Subcommittee on Water Resources and EnvironmentMinority member
- Subcommittee on Coast Guard and Maritime TransportationMinority member
- Subcommittee on Highways and TransitMinority member
- Committee on Veterans' AffairsMinority member
- Subcommittee on Disability Assistance and Memorial AffairsMinority member
- Subcommittee on Economic OpportunityMinority member
Source: House Clerk
More about themShow details
More about them
- Sworn in
- January 3, 2025 (current term)
- Next election
- 2026
- Born
- 1980
- Office in Washington
- 452 Cannon House Office Building
Sources: House Clerk, Library of Congress